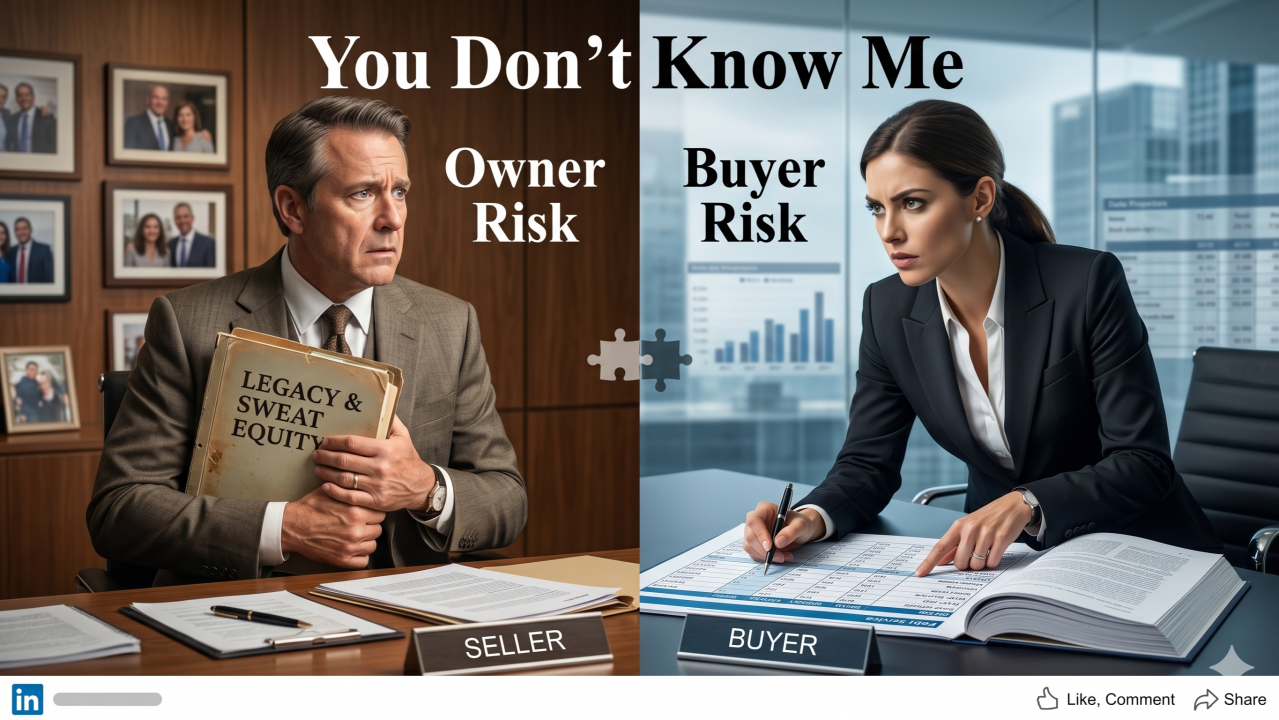
How buyers and sellers fail to understand the risk and opportunity in selling a business
Every engagement boils down to two questions.
To buyers: What will scare you most when you buy a business?
To sellers: What will hurt most when you sell?
The answers are never the same. And that gap, that invisible distance between what a buyer fears and what a seller mourns, is where most deals quietly fall apart.
Not because of price. Because of misunderstood risk.
Five Gaps. Nearly Every Deal.
There are five gaps that consistently separate deals that close cleanly from those that collapse, retrade, or close with regret: Time, Cash Flow, Identity, Integration, and Control.
Time. Sellers think in years. Buyers think in survival windows. A seller measures the business in what it cost them: years, relationships, identity. A buyer measures it in the short term and debt payments. These are not just different perspectives. They are different time signatures, and every negotiation suffers when neither party understands the other’s shot clock.
Cash flow. This drives the value. The seller sees the past as a record of what the business did. The buyer sees the future, full of question marks. Debt repayment. ROI. Every year ahead is stacked against what they paid today. Cash flow is not what the business did. It is what survives the transition.
Risk asymmetry. The seller risks regret. The buyer risks ruin. They are not the same, and treating them as such is a reliable path to a broken deal. The seller can walk away and still be fine (for now). The buyer, if things go wrong, often cannot.
Integration. The financial statements are visible. What actually transfers is not. Who stays when the seller walks away? Which customers were buying from a person, not a brand? What lived in the seller’s head and was never written down? The path every buyer walks after close is the same: stabilize, then understand, then improve. In that order. Not the other way around.
Competition or collaboration. The aggressive negotiator wants to win. Every concession feels like a loss. The result: price dominates, risk stays hidden, and both parties arrive at closing having protected themselves from each other rather than solving anything together. The best dealmakers do not negotiate harder. They diagnose better.
Where Deals Actually Break
Failures cluster at three points:
- Due diligence, when the numbers do not align with the story.
- Retrade, when price changes at the last minute because risk was not surfaced.
- Integration, when the business breaks down after close.
Almost every breakdown traces back to something left unsaid. Three phrases echo through every deal that fell apart:
“I thought…” “I assumed…” “That wasn’t clear…”
Three Questions. Every Deal.
Before you negotiate price, answer these about the person across the table:
RISK: What do they fear most? TIME: What horizon are they on? GOAL: What does “done” look like for them?
If you know those three things, you can solve almost anything. Every business sale is a negotiation between two people who think the other one does not understand them. Most of the time, they are right.
The ones who close well (without ruin, without regret) stopped trying to win and started trying to understand. They named the risk instead of hiding it. They asked the question they were afraid to ask.
There is one question I have seen close more gaps than almost any other: “If I were you…”
Approaching the sale as a collaborative problem to solve wins the day.
Don’t just present value. Reduce fear.
First published on LinkedIn.